Our Market Operations Weekly Report contains the latest information about the electricity market, including security of supply, wholesale price trends and system capacity.
It is published every Tuesday. Click here to receive the report via email every week.
If you have any comments or questions please contact the Market Operations Team at [email protected].
Latest Report / More Information
|
Image

|
|
Current Storage Positions
Overview
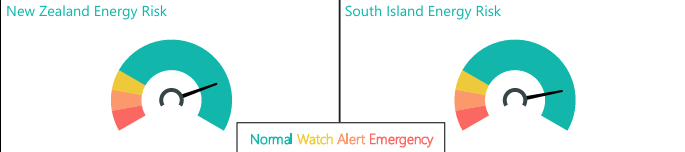
Renewable generation made up 98% of the mix this week. The increase in South Island inflows contributed to an increase in national hydro storage to 125% of the seasonal average from 114% the previous week.
In this week's insight we look at how the rise in embedded solar generation is resulting in bi-directional flows at grid exit points, and what this means operationally for real-time security.
Security of Supply and Capacity
Energy
National hydro storage increased to 125% of the seasonal average from 114% the week prior. Lower than average hydro generation and above average inflows in the South Island contributed to South Island storage increasing from 120% to 133%. While North Island storage decreased slightly from 77% to 74%.
Capacity
Residual generation was healthy last week. The lowest residual was 929 MW on the evening of Tuesday 27 October.
The N-1-G margins in the NZGB forecast are at healthy levels through to late December. Within seven days we monitor these more closely through the market schedules.. The latest NZGB report is available on the NZGB website.
Electricity Market Commentary
Weekly Demand
Total demand increased last week to 764 GWh from 747 GWh the week prior. The highest demand peak occurred at 7:30 am on Friday 30 October at 5,597 MW with cooler temperatures in parts of the country.
Weekly Prices
Wholesale electricity spot prices decreased last week with the average Ōtāhuhu price down to $36/MWh from $66/MWh the previous week. The Ōtāhuhu price peaked at $230/MWh at 9:00 pm on Tuesday 27 October, coinciding with lower wind generation and constrained HVDC northward flow.
Periods of inter-island energy price separation occurred throughout the week during periods of high HVDC northward transfer, with outages of lower North Island grid equipment lowering the northward transfer limit. This was also over the
weekend with lower geothermal generation during the WRK ring (WKM_WRK) outages.
Periods of intra-island energy price separation occurred in the North Island throughout the week This was due to constraints to protect BPE_TKU circuits with the HLY_SFD outage and high northward flow.
Generation Mix
Hydro generation was below average last week at 56%, down from 57% the week prior. Solar generation remained at its new record share of 4%. Wind increased to 15% of the mix, well above its average. The geothermal share decreased to 23% last week from 25% the week prior. A highly renewable generation mix this week left thermal and co-generation at around 1% of the mix each.
HVDC
HVDC flows last week were almost entirely northward, consistent with above average South Island hydro storage. In total 93 GWh was transferred north.
Consultations
We are consulting on the TSO:DSO coordination: operations requirements paper. Please send your feedback by email to [email protected] by 5pm on Friday 6 November 2026.
Ancillary Services Tender
The 2026 Ancillary Services tender has now closed. The System Operator invited tenders for the provision of Over-Frequency Reserve and South Island Black Start services.
Successful respondents will be offered contracts commencing 1 January 2027. Any questions about the tender process can be sent to [email protected].